HVAC Business MCA Restructuring: A Four-Funder Case Study
After losing a major customer, a commercial HVAC business owner needed room to cover operating expenses while finding new work. This case explains MCA Shield’s referral contribution, the original payment schedules and the ongoing restructuring arrangement reported by Shane Fitzgibbon.
By Shane Fitzgibbon, MCA Shield co-owner · Case account updated September 19, 2026 · Program ongoing
The business situation at enrollment
The owner had $243,500 in remaining obligations across four funders, according to Shane’s account of the enrollment file. Losing a major customer had left the operating business under pressure from a mixture of daily and weekly payments.
The remaining balance is different from the original repayment amounts printed in the contracts. The excerpts below document terms at origination; they do not establish later balances or actual withdrawals at enrollment.
What MCA Shield contributed
“We helped this owner connect with a relief provider after the loss of a major customer put pressure on the business. My role was on the intake and referral side; the provider arranged the repayment plan.” — Shane Fitzgibbon
Our matching process considers provider minimums, industry acceptance, the mix of funders and the services relevant to the business’s circumstances. We organize the information for review and explain a potential referral before requesting authorization to share the file.
MCA Shield provides financial consulting and referrals. Independent providers evaluate eligibility and deliver contracted services. Learn more about MCA debt relief options through MCA Shield or compare MCA relief providers.
Original payment schedules and the reported new arrangement
The excerpts show three daily payment schedules and one weekly schedule. The table converts daily amounts using five collection days per week. Agreements are identified by the original amounts visible in the excerpts because funder names are not visible within every crop.
| Agreement identifier | Original total repayment | Payment shown | Weekly equivalent |
|---|---|---|---|
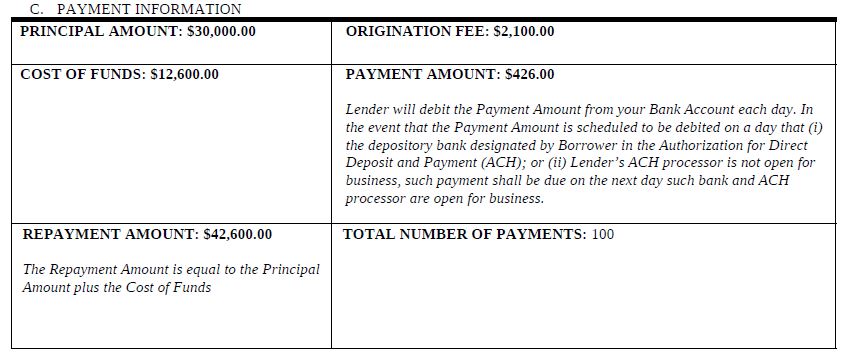
| $30,000 principal | $42,600 | $426 daily | $2,130 |
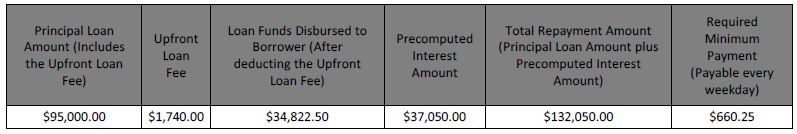
| $95,000 principal | $132,050 | $660.25 each weekday | $3,301.25 |
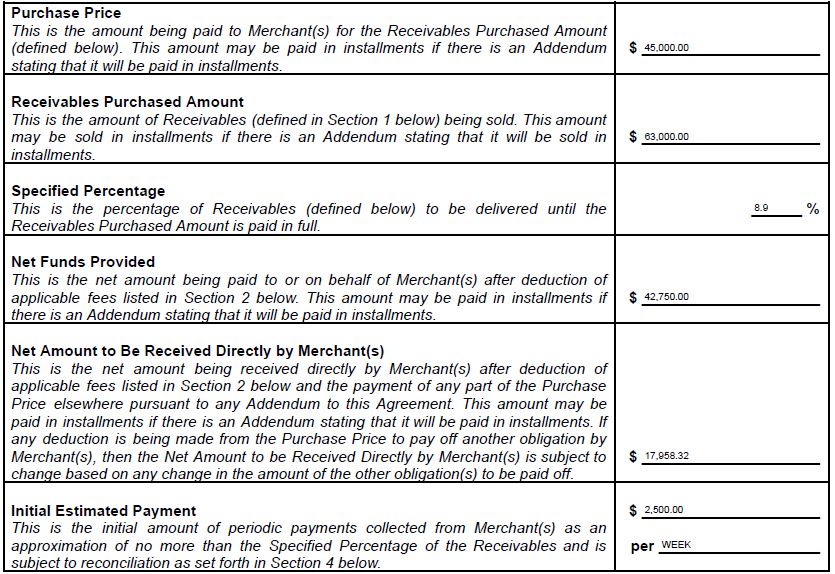
| $45,000 purchase price | $63,000 | $2,500 weekly, initially estimated | $2,500 |
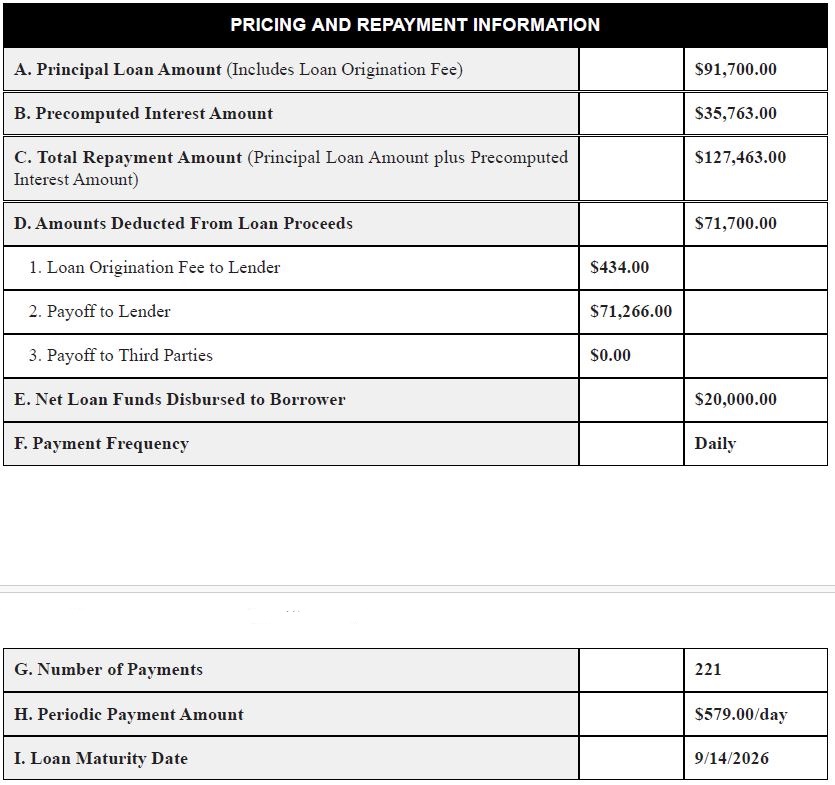
| $91,700 principal | $127,463 | $579 daily | $2,895 |
| Original contract totals—not enrollment balances | $365,113 | Three daily; one weekly | $10,826.25 |
Remaining balance at enrollment: $243,500. The $365,113 above is the combined original contractual repayment amount before subsequent payments. It is not the balance enrolled in the restructuring plan.
Shane reports that the provider arranged a 52-week restructuring and balance-reduction plan at $4,145.67 per week, including program fees, designed to satisfy all four obligations. He reports that this gave the owner more room to cover overhead and seek replacement customers.
How the payment comparison is calculated
($426 + $660.25 + $579) × 5 collection days + $2,500 = $10,826.25 per week.
Comparing that amount with $4,145.67 gives a difference of $6,680.58 per week, or approximately 61.7%.
Monthly equivalents: The original schedules equal $46,913.75 per month; the reported new payment equals $17,964.57 per month. Both use weekly payments × 52 ÷ 12, rather than a four-week month. The difference is $28,949.18 per average month, approximately 61.7%.
This is a comparison with the original contractual schedules, assuming all four were active together and unchanged. It is not a verified comparison of bank withdrawals at enrollment. Holidays, payment adjustments or different collection patterns could change the baseline. The percentage describes periodic payments—not a 61.7% reduction in balances.
The new agreement, fee breakdown and payment ledger are not reproduced here. The new terms and remaining enrollment balance are reported by Shane, rather than independently verified by the original contract excerpts. The program is ongoing; this page does not claim completed repayment or final releases.
Original funding agreement excerpts
These excerpts support the original terms summarized above. They are not evidence of the later negotiated arrangement or of completed program payments. Some show proceeds allocated to earlier obligations; they should not be read as four amounts of fresh cash received at enrollment.
What this case illustrates—and what it does not
A combined view of daily and weekly obligations makes payment pressure easier to understand. It also helps distinguish a change in payment frequency, an extended schedule and a negotiated balance reduction. Those are separate features of a proposal.
This case describes one arrangement reported by Shane. It does not establish typical results, guarantee creditor participation or show that another business would qualify. MCA Shield does not have aggregate outcome data establishing an expected reduction.
For background, read about MCA payment restructuring, settlement and balance reductions and reviewing daily MCA payment pressure. If a proposal involves owner liability, review questions about personal guarantees and written releases.
Explore your MCA relief options
Tell us what your business owes, what it is paying and what has changed. A free consultation can help organize your situation for a potential provider referral.