A Merchant Cash Advance, often called an MCA, can seem like a quick and convenient solution when your business needs fast access to capital. Unlike traditional loans, Merchant Cash Advances are designed to provide funding quickly, often with minimal paperwork and fast approval times. For business owners dealing with cash flow shortages, urgent expenses, payroll concerns, or unexpected operational costs, an MCA can appear to offer immediate relief.
What many business owners do not fully realize, however, is how Merchant Cash Advances actually work — and how quickly they can create financial strain if repayment terms become difficult to manage. Understanding how MCA funding is structured, how repayment is collected, and what risks may come with this type of financing is critical before accepting one. Knowing the full picture can help business owners make informed financial decisions and avoid becoming trapped in a cycle of aggressive daily withdrawals and stacked debt obligations.
Schedule Your Free Consultation
What Exactly Is a Merchant Cash Advance?
A Merchant Cash Advance is a type of business funding where a company provides your business with a lump sum of money upfront in exchange for a portion of your future sales or receivables.
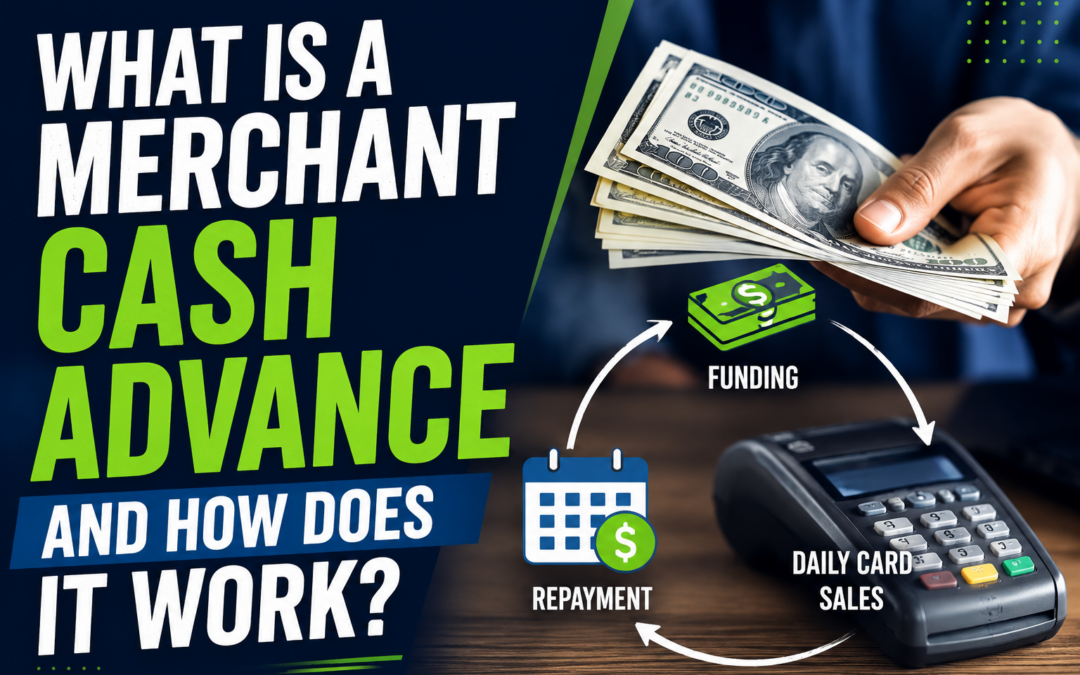
Unlike a traditional business loan, this is not technically structured as a loan. Instead, it is considered a purchase of future revenue. The MCA provider gives your business immediate capital and collects repayment directly from your daily or weekly revenue until the agreed amount has been repaid.
Because approval is often based more on revenue performance than credit history, Merchant Cash Advances are commonly marketed to businesses that may not qualify for traditional bank financing.

How Does a Merchant Cash Advance Work?
The process is usually straightforward.
A business applies for funding and provides recent bank statements, revenue records, and other financial documentation. Once approved, the MCA provider advances a lump sum to the business.
Repayment is then automatically collected through one of two common methods:
- Daily or weekly ACH withdrawals directly from your business bank account
- A percentage of future credit card sales
The total amount repaid is determined using a factor rate rather than a traditional interest rate.
For example, if a business receives $50,000 with a factor rate of 1.4, the total repayment obligation becomes $70,000.
This means the business must repay the original advance plus $20,000 in fees.
How MCA Repayment Is Different From Traditional Business Loans
Traditional business loans generally have:
- Fixed monthly payments
- Lower interest rates
- Longer repayment terms
- Clear amortization schedules
Merchant Cash Advances often involve:
- Daily or weekly automatic withdrawals
- Higher effective borrowing costs
- Short repayment periods
- Less regulatory oversight
This structure can create significant pressure on daily cash flow, especially during slower revenue periods.
What Business Owners Use Merchant Cash Advances For
Businesses often use Merchant Cash Advances to cover:
- Payroll shortages
- Emergency operational expenses
- Inventory purchases
- Equipment repairs
- Seasonal cash flow gaps
- Expansion opportunities
While these funding needs are legitimate, the speed of MCA approval can sometimes lead business owners to accept terms without fully understanding the long-term financial impact.
The Real Cost of Merchant Cash Advances
One of the biggest misunderstandings surrounding Merchant Cash Advances is cost.
Because MCA providers use factor rates instead of APR, the true cost can be difficult to calculate at first glance.
What may appear to be a manageable repayment amount can translate into an extremely high effective annualized cost, especially when repayment occurs over a short period.
For many businesses, these aggressive repayment schedules create ongoing financial strain.
Why Merchant Cash Advances Can Become Dangerous
Problems often begin when daily withdrawals start interfering with operating cash flow.
Business owners may struggle to:
- Cover payroll
- Pay vendors on time
- Maintain working capital
- Handle seasonal fluctuations
In some cases, businesses take out additional advances to cover existing MCA obligations.
This creates stacked debt, one of the most dangerous financial situations for a business.
Common Merchant Cash Advance Terms You Should Understand
Important MCA terms include:
Factor Rate: Multiplier used to determine total repayment
Holdback Percentage: Portion of daily revenue collected
ACH Withdrawal: Automated daily bank account deduction
Stacking: Taking multiple MCAs simultaneously
Reconciliation Clause: Potential adjustment based on actual revenue
Understanding these terms helps business owners evaluate risk before signing an agreement.
Warning Signs Your MCA Is Hurting Cash Flow
Your Merchant Cash Advance may be becoming a problem if:
- You are constantly low on operating cash
- Payroll feels difficult to meet
- You are delaying vendor payments
- Daily withdrawals are causing overdrafts
- You are considering another MCA to stay current
These are often early indicators that relief may be necessary.
Can You Get Out of Merchant Cash Advance Debt?
Yes. Businesses facing MCA pressure often have options.
These may include:
- Debt restructuring
- Payment renegotiation
- MCA consolidation
- Settlement negotiations
- Professional relief assistance
The earlier action is taken, the more options are typically available.
When To Seek Merchant Cash Advance Relief
If your business is struggling to keep up with daily withdrawals, it may be time to explore professional relief options.
Merchant Cash Advance relief can help businesses regain control, stabilize cash flow, and create a realistic path forward.
Ignoring the problem often allows financial pressure to escalate.
Struggling With Merchant Cash Advance Payments?
If daily withdrawals are putting pressure on your business, you may have options. MCA Shield helps business owners explore practical Merchant Cash Advance relief solutions designed to restore cash flow and create a path toward financial stability.
The sooner you act, the more options may be available.
How to Reduce MCA Payments by 40% or More
See how one business reduced Merchant Cash Advance payments by 40% through strategic MCA debt relief. Learn the process, challenges, and solutions that helped restore cash flow.
How to Get Out of Merchant Cash Advance Debt Legally
Merchant cash advance debt can pull a business into a difficult cycle fast. What starts as quick access to funding can turn into nonstop pressure on your cash flow. Daily withdrawals chip away at the money your business needs to operate. Stacked advances often make...
MCA Debt Relief Guide: What Business Owners Need to Know
Merchant cash advance debt can quickly become overwhelming for business owners trying to maintain healthy cash flow while keeping operations running smoothly. As daily or weekly MCA payments increase, many companies find themselves trapped in a cycle of stacked...
How To Stop Daily ACH Debits From MCA Lenders
If your business is struggling with overwhelming merchant cash advance payments, you may be wondering how to stop daily ACH debits from MCA lenders before they completely destroy your cash flow. Many business owners become trapped in a cycle of aggressive daily...
What Is a Reverse MCA? Why Reverse MCA Consolidation Often Makes Things Worse
Reverse MCA consolidation is often marketed as a way to simplify multiple merchant cash advance payments, but it can create even bigger financial problems. By replacing existing MCAs with a new, larger advance, businesses may face higher repayment costs, longer repayment terms, and continued cash-flow pressure. Learn how reverse MCA consolidation works, why it often makes debt worse, and what alternatives may provide more effective relief.
Why Is My Business Bank Account Empty? Top 10 Causes of Cash Flow Problems
If your business bank account is empty—even though sales are coming in—you’re not imagining things, and you’re definitely not alone. Many business owners discover their account balance dropping to zero with no clear explanation, often overnight or within days of...
How to Get Out of MCA Loans Without Defaulting
When contemplating how to get out of mca loans, the situation can feel impossible to escape. Daily withdrawals drain bank accounts, cash flow becomes unpredictable, and many business owners are left reacting to problems instead of running their businesses. As pressure...
Merchant Cash Advance Payment Reduction Without Defaulting
For many business owners, merchant cash advance payments feel permanent. Once daily withdrawals begin, it can seem as though there is no way to reduce them without triggering default, legal pressure, or aggressive collection activity. That perception often leads...
MCA Debt Relief: What Business Owners Need to Know Before Defaulting
Struggling with MCA payments? Learn what business owners need to know before defaulting, including warning signs, debt settlement options, and immediate steps to protect cash flow.
Why Merchant Cash Advance Withdrawals Drain Your Bank Account — And What to Do Next
Daily merchant cash advance ACH withdrawals can drain a business bank account by pulling fixed payments every day, regardless of revenue fluctuations. Over time, these daily MCA withdrawals often take more cash than a business can realistically sustain, leaving...