
ClickCease
Explore options for your business’s MCA payments.Call (918) 608-0117

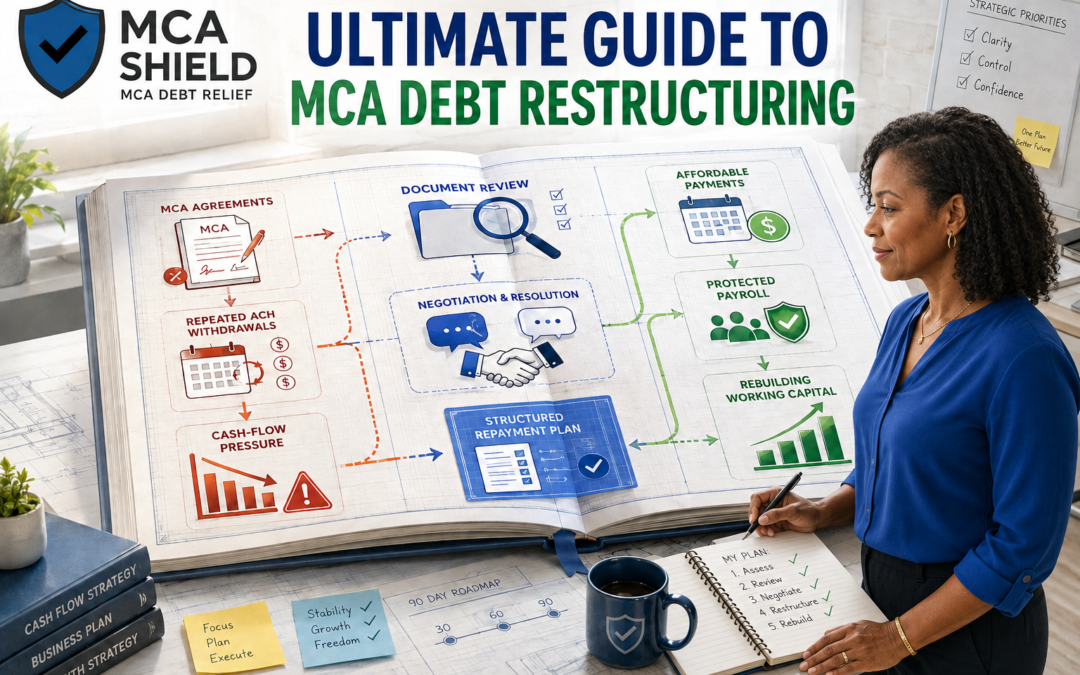
This MCA debt restructuring guide explains how businesses can address overwhelming daily or weekly payments before cash-flow pressure becomes unmanageable. When multiple withdrawals begin affecting payroll, vendors, taxes, and operating expenses, restructuring may provide a more sustainable path forward.

You will learn how the process works, how affordable payments are calculated, what happens during negotiations, and how UCC filings and personal guarantees may be handled. Most importantly, this guide will help you understand your options, avoid costly mistakes, and make informed decisions that protect your business and working capital.

Schedule Your Free Consultation

What Is MCA Debt Restructuring and How Does It Work?

MCA debt restructuring is the process of reviewing existing merchant cash advance obligations and pursuing more manageable payment arrangements. The goal is to reduce immediate cash-flow pressure while creating a payment structure the business can realistically maintain.

The process usually begins with a complete review of MCA agreements, remaining balances, withdrawals, revenue, and essential operating expenses. This information helps determine what the business can afford without sacrificing payroll, taxes, inventory, or working capital.

How Restructuring Changes Existing MCA Payment Terms

MCA restructuring may change the amount, frequency, or timing of payments. For example, frequent ACH withdrawals may be reduced or moved to a schedule that better reflects the business’s current revenue.

Depending on the provider and agreement, restructuring may involve:

  • Lower daily or weekly withdrawals
  • A longer repayment timeline
  • Temporary payment adjustments
  • Modified payment dates
  • One coordinated payment strategy for multiple MCAs
  • Negotiated payoff or settlement terms

Lower payments may provide immediate relief, but they can also extend the payment period. Therefore, the business should review the total cost, not just the new payment amount.

Any revised arrangement should be provided in writing. The document should clearly explain the payment schedule, fees, remaining obligation, and conditions the business must follow.

MCA Debt Restructuring vs. Refinancing or Consolidation

Although these terms are sometimes used interchangeably, they can describe different solutions.

MCA debt restructuring generally focuses on modifying or negotiating existing obligations. It does not necessarily require the business to take on a new loan or cash advance.

Refinancing typically involves obtaining new financing to pay off existing MCA obligations. The business then repays the new lender under a different set of terms. Approval may depend on credit, revenue, collateral, and overall financial health.

MCA consolidation may combine several payments into one structured payment. However, some consolidation programs use new financing, while others coordinate or restructure existing obligations. Business owners should ask exactly how the program works before enrolling.

The best option depends on the number of MCAs, current cash flow, repayment history, credit profile, and ability to qualify for traditional financing.

What Restructuring Does Not Automatically Eliminate

Restructuring does not automatically erase an MCA obligation. Unless the provider agrees otherwise in writing, the business may remain responsible for the negotiated balance and revised payments.

It also does not automatically remove:

  • UCC filings
  • Personal guarantees
  • Existing defaults or missed payments
  • Contractual fees
  • Collection activity
  • Pending legal claims
  • Obligations under the original agreement

A UCC filing may remain active until the obligation is resolved and the appropriate termination document is filed. Likewise, a personal guarantee may continue unless the provider expressly releases it.

Business owners should never assume that reduced payments mean the original agreement has been canceled. Every proposed restructuring plan should be reviewed carefully so the business understands the changes, what remains enforceable, and what is required for final resolution.

How to Measure the Full MCA Burden on Your Business

Before choosing an MCA debt restructuring strategy, you need to understand the complete financial burden. Looking at one withdrawal or one agreement is not enough. The real impact comes from how every MCA payment interacts with payroll, vendors, taxes, rent, and other essential expenses.

A complete review helps reveal whether the current payment structure is sustainable and what the business can realistically afford.

Calculate Your Total Daily and Weekly Withdrawals

Start by listing every automatic MCA withdrawal from the business bank account. Include withdrawals made under different provider names or payment-processing descriptions.

Record the following information for each MCA:

  • Provider name
  • Daily or weekly withdrawal
  • Number of withdrawals per week
  • Payment method
  • Remaining payment schedule
  • Estimated payoff amount

Next, calculate the combined burden.

For example, if three MCA providers withdraw $350, $275, and $225 each business day, the total daily burden is $850. Over five business days, those withdrawals remove $4,250 per week from operating cash.

Compare the combined withdrawals with the business’s average weekly deposits. This reveals the percentage of incoming revenue being consumed before the business can pay its regular expenses.

Review at least three months of bank activity whenever possible. A longer review helps account for seasonal revenue, inconsistent deposits, returned payments, and unusually strong or weak weeks.

Identify Factor Rates, Remaining Balances, and Fees

The original advance amount does not represent the total repayment obligation. Most MCA agreements use a factor rate to determine the purchased amount or total payback.

For example, a $50,000 advance with a factor rate of 1.40 may require approximately $70,000 in total payments, excluding additional fees.

Review each agreement for:

  • Original advance amount
  • Factor rate
  • Total purchased amount or repayment obligation
  • Amount already paid
  • Estimated remaining balance
  • Origination or administrative fees
  • Default or returned-payment fees
  • Collection or legal costs
  • Prepayment provisions

Do not estimate the remaining obligation based only on the original funding amount. Request an updated payment history or payoff statement from each provider when available.

This step is especially important when the business has renewed or stacked multiple MCAs. A renewal may pay off part of an earlier advance while adding a new obligation, making the true balance difficult to identify without complete records.

Determine How Much Operating Cash the Business Actually Needs

Affordable payments should be based on what remains after the business covers its essential operating expenses. They should not be based on revenue alone.

Begin with the business’s average weekly or monthly deposits. Then subtract expenses such as:

  • Payroll and payroll taxes
  • Rent or mortgage payments
  • Inventory and materials
  • Utilities and insurance
  • Vendor obligations
  • Equipment and vehicle costs
  • Tax payments
  • Minimum working-capital reserves

The amount left after essential expenses represents the cash potentially available for MCA payments. However, the business should also maintain a reasonable reserve for revenue changes, emergencies, and unexpected costs.

A payment may appear affordable during a strong week but become impossible during a slower period. Therefore, use realistic average revenue and account for seasonal declines.

This calculation provides the foundation for a sustainable restructuring proposal. It allows the business to pursue payments that address its MCA obligations without creating another immediate cash-flow crisis.

Warning Signs Your Business May Need MCA Debt Restructuring

MCA debt restructuring warning signs showing withdrawals threatening payroll, taxes, vendors, inventory, and operating cash

MCA payment problems rarely appear without warning. The pressure usually builds as withdrawals consume more revenue, leaving less cash available for normal operations.

Recognizing these warning signs early may give the business more options. Waiting until several payments have failed can make negotiations more difficult and increase the risk of collections or legal action.

MCA Withdrawals Are Disrupting Payroll and Essential Expenses

One of the clearest warning signs is having revenue to operate but not enough available cash after MCA withdrawals. Daily or weekly payments may leave the bank account before the business can cover its most important expenses.

Warning signs include:

  • Delaying payroll or payroll taxes
  • Paying vendors later than usual
  • Falling behind on rent or utilities
  • Postponing equipment repairs
  • Reducing inventory purchases
  • Using personal funds for business expenses
  • Moving money between accounts to prevent shortfalls

These problems demonstrate that the existing payment structure may no longer match the business’s cash flow.

Revenue alone does not determine whether MCA payments are affordable. A business can generate strong sales and still face a cash-flow crisis when MCA payments are withdrawn before enough sales revenue comes in.

When essential expenses repeatedly compete with MCA payments, it may be time to explore MCA debt restructuring before operations are disrupted further.

Renewals or Additional Advances Are Covering Cash-Flow Gaps

Another warning sign is relying on new MCA funding to replace cash drained by existing withdrawals. The additional funding may provide temporary relief, but it also creates another payment obligation.

This can lead to a costly cycle:

  1. Existing withdrawals reduce operating cash.
  2. The business accepts another advance to cover expenses.
  3. The new advance adds another daily or weekly withdrawal.
  4. Cash-flow pressure returns at a higher level.
  5. Another renewal or advance appears necessary.

This pattern is commonly associated with MCA stacking. Instead of solving the underlying cash-flow problem, each new advance may increase the percentage of revenue committed to repayment.

Renewals also deserve careful review. A provider may offer additional funding before the current obligation is fully satisfied. However, part of the new advance may be used to pay the previous balance, leaving the business with less usable cash than expected.

If new funding is primarily being used to make existing MCA payments, the business may need a restructuring strategy rather than another advance.

Overdrafts, Returned Payments, and Collection Pressure Are Increasing

Frequent overdrafts and returned ACH withdrawals indicate that the business bank account can no longer support the current payment schedule.

Early warning signs may include:

  • Repeated insufficient-funds fees
  • Negative account balances
  • Returned ACH withdrawals
  • Frozen or restricted payment-processing activity
  • Increased calls or emails from MCA providers
  • Default notices or demand letters
  • Contact with customers, vendors, or payment processors
  • Threatened or pending legal action

Returned payments can also trigger additional fees and default provisions. As a result, the remaining obligation may grow while the business has even less money available.

Communication often becomes more urgent after payments begin failing. Business owners should document calls, emails, notices, payment histories, and any proposed arrangements. They should also avoid making promises the business cannot keep.

Increasing collection pressure is a sign that immediate action may be necessary. Reviewing the agreements and cash flow early can help the business understand its options before the situation becomes more expensive and difficult to control.

The MCA Debt Restructuring Process From Review to Resolution

MCA restructuring payment calculation protecting payroll, taxes, vendors, operating expenses, and working capital before determining an affordable payment

The MCA debt restructuring process begins with a complete financial review and ends with a clearly documented payment arrangement. Each stage should help the business understand its obligations, establish an affordable payment range, and avoid agreements that create additional financial pressure.

Although every situation is different, most restructuring efforts involve three essential steps.

Gather Agreements, Bank Statements, and Payment Records

The first step is collecting accurate information for every merchant cash advance. Missing agreements or incomplete payment records can make it difficult to calculate the total obligation or identify important contract terms.

Gather documents such as:

  • Every current MCA agreement
  • Recent business bank statements
  • ACH withdrawal records
  • Payment-processing statements
  • Updated payment histories
  • Payoff or balance statements
  • Default notices and collection letters
  • Emails or written payment arrangements
  • Payroll, tax, rent, and vendor records

Bank statements should show the business’s deposits, withdrawals, overdrafts, and seasonal revenue changes. Reviewing several months of activity provides a more accurate picture than relying on one unusually strong or weak month.

Each agreement should also be checked for payment terms, reconciliation provisions, UCC filing language, personal guarantees, default provisions, and additional fees.

The goal is to create a reliable summary of the business’s MCA obligations and cash-flow needs.

Build a Complete Restructuring Strategy

Once the documents are organized, the business can determine the type of payment arrangement that may be sustainable.

The strategy should consider:

  • Total daily and weekly MCA withdrawals
  • Remaining obligations
  • Average business revenue
  • Essential operating expenses
  • Seasonal changes
  • Working-capital needs
  • Existing defaults or returned payments
  • Collection and legal activity
  • UCC filings and personal guarantees

An affordable payment should leave enough cash for payroll, taxes, vendors, rent, inventory, and other critical expenses. It should also include room for unexpected costs or slower revenue periods.

A complete strategy may seek lower withdrawals, less frequent payments, a longer payment timeline, or coordinated arrangements involving multiple MCA providers. However, the lowest immediate payment is not always the best option. Extending the timeline may increase the total amount paid.

For that reason, the business should compare the proposed payment, repayment period, fees, and total cost before making a decision.

Negotiate and Document the Revised Payment Arrangement

After establishing an affordable payment range, discussions can begin with the MCA provider or its representatives. The business may need to explain its current financial condition and provide records supporting the requested payment adjustment.

Negotiations may address:

  • Reduced daily or weekly payments
  • Changes to payment frequency
  • Temporary payment relief
  • Extended repayment terms
  • Waived or reduced fees
  • Negotiated payoff terms
  • Arrangements for multiple obligations

No specific outcome is guaranteed. The available options depend on the agreement, payment history, financial condition, and whether each provider is willing to modify the arrangement.

Most importantly, the business should obtain the final terms in writing before relying on them. The written arrangement should identify the payment amount, schedule, remaining obligation, fees, default conditions, and what happens after the final payment.

Verbal promises can be misunderstood or disputed later. Therefore, the business should keep copies of every signed agreement, email, payment confirmation, and updated account statement.

A restructuring process is not complete simply because withdrawals have decreased. Resolution comes when the revised terms are clear, affordable, consistently followed, and properly documented.

How Affordable MCA Restructuring Payments Are Calculated

Affordable MCA restructuring payments should be based on the cash the business can consistently generate after covering essential expenses. A payment is not truly affordable if it forces the owner to delay payroll, miss tax obligations, or rely on another advance.

The calculation should use verified financial records rather than estimates or one unusually profitable month.

Start With Revenue and Essential Operating Expenses

Begin by calculating the business’s average weekly or monthly revenue. Review several months of bank and payment-processing statements to account for seasonal changes, slow periods, and irregular deposits.

Next, subtract essential operating expenses, including:

  • Payroll and employee benefits
  • Rent or mortgage payments
  • Utilities and insurance
  • Inventory and materials
  • Equipment and vehicle costs
  • Taxes and licensing expenses
  • Vendor payments
  • Necessary marketing expenses
  • Existing loan payments

The amount remaining after these expenses helps establish the business’s available cash flow. However, the entire remaining amount should not automatically be committed to MCA payments. The business still needs a cushion for unexpected expenses and revenue changes.

For example, suppose a business generates an average of $30,000 per week and requires $24,000 for essential expenses and reserves. That leaves approximately $6,000 before accounting for an affordable MCA payment and additional financial protection.

The final payment should reflect normal operating conditions, not the best possible week.

Protect Payroll, Taxes, Vendors, and Working Capital

A restructuring plan should allow the business to continue operating while addressing its MCA obligations. That means protecting the expenses that keep the company open and producing revenue.

Payroll should remain a priority because missed wages can lead to employee turnover and operational problems. Payroll taxes must also be set aside rather than treated as available cash.

Likewise, the business needs enough money to pay vendors and purchase inventory or materials. Falling behind can damage important relationships, interrupt service, and prevent the company from completing revenue-producing work.

Working capital is equally important. It provides the short-term cash needed to manage expenses while waiting for customer payments or future sales.

Before accepting a restructured payment, confirm that the business can still:

  • Pay employees on time
  • Reserve money for taxes
  • Maintain essential inventory
  • Keep vendor accounts current
  • Cover rent, utilities, and insurance
  • Handle unexpected operating costs
  • Maintain a reasonable cash reserve

A restructuring plan that consumes all available cash may temporarily address MCA payments while creating new problems elsewhere.

Avoid Accepting Payments the Business Cannot Sustain

A reduced payment can look attractive when the business is under immediate pressure. However, the proposed amount must remain manageable during both strong and slow revenue periods.

Before agreeing to revised terms, ask:

  • Can the business make this payment during its slowest month?
  • Will payroll and taxes still be covered?
  • Does the payment leave enough working capital?
  • Are additional fees included?
  • How long will the revised arrangement continue?
  • What happens if revenue drops unexpectedly?
  • Will one missed payment cancel the agreement?

The business should also review whether the proposed arrangement includes automatic increases, large final payments, or strict default provisions. These terms can create another cash-flow crisis later.

If the business cannot cover the payment without overdrafts, delayed expenses, or new borrowing, the payment is not affordable.

A sustainable MCA debt restructuring plan should provide enough breathing room for the business to operate, stabilize its finances, and complete the revised payment arrangement without restarting the debt cycle.

What Happens During MCA Restructuring Negotiations?

During MCA restructuring negotiations, the business or its representative communicates with MCA providers about changing the current payment arrangement. The goal is to present the financial situation clearly and pursue terms the business can maintain.

Negotiations may involve several conversations, document requests, and revised proposals. MCA providers are not required to accept every request, and results can vary based on the agreement, payment history, and financial circumstances.

How Payment Frequency and Amounts May Be Addressed

The existing withdrawal amount is often one of the first issues discussed. If daily ACH payments are creating severe cash-flow pressure, the business may request a lower amount or a different payment schedule.

Possible payment adjustments may include:

  • Lower daily withdrawals
  • A change from daily to weekly payments
  • Temporary payment reductions
  • Extended payment timelines
  • Modified withdrawal dates
  • Coordinated payments across multiple MCAs
  • Negotiated payoff arrangements

Some MCA agreements include a reconciliation provision that may allow payments to be adjusted based on actual receivables. The business should review the agreement carefully to determine whether this option exists and what documentation is required.

A lower payment can provide immediate relief, but it may also extend the payment period. Therefore, the business should compare the proposed payment amount with the total repayment cost.

The requested terms should reflect the amount the business can consistently afford—not simply the lowest amount it hopes the provider will accept.

Why Clear Financial Documentation Strengthens Negotiations

Clear, organized financial records help providers understand the seriousness of a business’s cash-flow problem.

Helpful documentation may include:

  • Recent business bank statements
  • Payment-processing reports
  • Profit-and-loss statements
  • MCA payment histories
  • Payroll records
  • Tax obligations
  • Vendor invoices
  • Rent and utility expenses
  • Current accounts receivable
  • Seasonal revenue comparisons

These records show how much money enters the business, how much is withdrawn, and what remains for essential operations. They can also demonstrate that the requested payment is based on actual financial conditions.

Incomplete or inconsistent records may weaken the request. For example, asking for a major payment reduction without showing revenue or operating expenses gives the provider little information to evaluate.

Accurate documents also help prevent the business from offering more than it can afford. A clear financial review supports a proposal that protects both continued operations and the revised payment arrangement.

What to Review Before Accepting Revised Terms

A verbal agreement or reduced withdrawal is not enough. Before accepting revised terms, the business should request a complete written explanation of the arrangement.

Review the following details:

  • New payment amount
  • Payment frequency
  • First payment date
  • Length of the revised schedule
  • Remaining obligation
  • Total amount expected to be paid
  • Additional restructuring or administrative fees
  • Default and missed-payment provisions
  • Automatic payment increases
  • Large final or balloon payments
  • Prepayment terms
  • UCC filing and personal guarantee language
  • Conditions for completing the arrangement

The business should also confirm whether the revised agreement replaces, modifies, or supplements the original MCA contract. If multiple documents remain active, each one should be reviewed for conflicting terms.

Never assume that a payment reduction removes prior defaults, fees, UCC filings, or personal guarantees. Any release or modification should appear clearly in writing.

Finally, compare the revised payment with realistic cash flow. If the business must delay payroll, taxes, vendors, or other essential expenses to comply, the proposed arrangement may not provide meaningful relief.

The strongest negotiated terms are not simply those with the lowest immediate payment. They are the terms the business understands, can document, and can sustain through completion.

How Are UCC Filings, Personal Guarantees, and Legal Risks Handled?

MCA agreement review showing UCC filing, personal guarantee, default provisions, collection activity, and written restructuring terms

MCA agreements may contain more than payment terms. They can also include UCC filing authorizations, personal guarantees, default provisions, and collection remedies.

Restructuring does not automatically remove these obligations. Each agreement requires careful review so the business understands what remains active and what may change under revised terms.

Because contract language and state laws vary, business owners should seek qualified legal guidance when facing a lawsuit, asset claim, account restriction, or other serious legal action.

What a UCC Filing Means During Restructuring

An MCA provider may file a UCC-1 financing statement to give public notice of its claimed security interest in certain business assets. Depending on the agreement, the filing may cover receivables, inventory, equipment, bank proceeds, or other assets.

A UCC filing does not automatically mean the provider owns or has seized those assets. However, it can affect the business’s ability to obtain financing because other lenders may discover the filing during underwriting.

During restructuring, an active UCC filing may remain in place until the business satisfies the obligation or reaches another written resolution with the provider.

Before accepting revised terms, determine:

  • Which business assets the filing covers
  • When the filing was recorded
  • Whether other providers have additional filings
  • What the revised agreement says about the filing
  • When the provider will authorize a UCC termination
  • Who is responsible for filing the termination document

Completing a revised payment plan does not always remove a filing from public records right away. The business should obtain written confirmation of the resolution and verify that the appropriate termination statement has been filed.

Why Personal Guarantees Require Careful Review

A personal guarantee may allow an MCA provider to pursue the business owner personally under certain circumstances. However, the scope of the guarantee depends on the exact contract language.

Some guarantees may apply after specific events, such as:

  • Diverting receivables
  • Blocking authorized withdrawals
  • Closing or changing bank accounts
  • Providing inaccurate financial information
  • Selling business assets outside normal operations
  • Violating other contract requirements

Business owners should not assume that restructuring automatically releases a personal guarantee. Unless the provider agrees to remove it or make a written modification, the guarantee may remain part of the arrangement.

Before signing revised terms, review:

  • The actions that can activate the guarantee
  • Which personal assets may face potential exposure
  • Whether the revised agreement expands the guarantee
  • Whether prior defaults remain active
  • What happens after the final payment
  • Whether the provider will issue a written release

Personal guarantees can create consequences beyond the business itself. An attorney can help explain the language and evaluate the owner’s potential exposure.

How Default and Collection Activity Can Affect the Process

Missed or returned payments may trigger default provisions in an MCA agreement. Once a provider declares a default, the contract may allow additional fees, accelerated collection efforts, or other remedies.

Collection activity may include:

  • Frequent calls and emails
  • Formal default notices
  • Demands for immediate payment
  • Attempts to reach payment processors
  • Claims against receivables
  • Contact with customers or account debtors
  • Arbitration or litigation
  • Enforcement of contractual remedies

Default can make restructuring more urgent, but it does not always make negotiation impossible. Clear communication and accurate financial records may still help the parties evaluate a revised arrangement.

The business should document every payment, notice, phone call, email, and proposal. It should also avoid ignoring legal documents or court deadlines. Missing a response date can reduce the business’s available options.

Most importantly, owners should not take actions that may violate the agreement without understanding the potential consequences. Closing a bank account, stopping payments, or redirecting receivables can create additional risk under some contracts.

A careful restructuring strategy should address both cash flow and legal exposure. The business needs to understand what remains attached to the agreement, what the provider may enforce, and what written steps will resolve each obligation.

How to Protect Business Operations While Restructuring MCA Debt

Restructuring should do more than reduce immediate payment pressure. It should help the business continue to serve customers, pay employees, and produce revenue throughout the process.

A strong MCA debt restructuring strategy protects daily operations while the business works toward a final resolution.

Maintain Enough Cash for Daily Operating Costs

Begin by identifying the expenses the business must pay to remain operational. These costs should guide the payment amount proposed during restructuring.

Essential expenses may include:

  • Payroll and payroll taxes
  • Rent or mortgage payments
  • Utilities and insurance
  • Inventory and materials
  • Vendor obligations
  • Equipment and vehicle costs
  • Tax payments
  • Software and payment-processing fees
  • Necessary marketing expenses

Create a weekly cash-flow schedule that shows when revenue enters the account and when each expense becomes due. This makes it easier to identify periods when multiple payments compete for the same money.

The business should also maintain a reasonable working-capital reserve. Committing every available dollar to MCA payments may leave no protection against equipment repairs, delayed customer payments, or seasonal revenue changes.

Review cash flow regularly during restructuring. If actual revenue differs significantly from the original projection, the business may need to adjust its operating budget or discuss the payment arrangement before another shortfall occurs.

Avoid New MCA Debt and the Renewal Cycle

Taking another merchant cash advance may appear to solve an immediate problem. However, new funding can add another withdrawal and restart the same cash-flow cycle the business is trying to escape.

A common pattern develops when:

  1. Existing MCA payments reduce operating cash.
  2. The business accepts new funding to cover expenses.
  3. Another withdrawal begins.
  4. Available cash decreases again.
  5. The business needs another renewal or advance.

Before accepting new funding, calculate how much usable cash the business will receive after paying origination costs, prior balances, and other deductions. Then compare that amount with the total new repayment obligation.

A renewal may provide less working capital than expected if part of the funding pays off an earlier advance. Even when the daily payment appears similar, the transaction may extend the repayment period or increase the overall cost.

During restructuring, new MCA debt may also affect existing negotiations. It can change the business’s available cash and make the proposed payment plan harder to maintain.

Instead, look for operational solutions such as reducing nonessential expenses, improving invoice collection, renegotiating vendor terms, or adjusting inventory purchases.

Track Withdrawals, Agreements, and Communication Carefully

Accurate records help the business verify payments, identify errors, and demonstrate compliance with revised terms.

Maintain a central record containing:

  • Every original MCA agreement
  • All revised payment arrangements
  • Provider contact information
  • Daily or weekly withdrawal amounts
  • Payment dates and confirmation numbers
  • Updated balance or payoff statements
  • Default and collection notices
  • Emails, letters, and written proposals
  • Notes from phone conversations
  • UCC filing and termination records

Review the business bank account frequently. Confirm that each withdrawal matches the written arrangement and note any unexpected payment, fee, or duplicate debit.

After important phone conversations, request written confirmation of any change in the agreement or payment. A verbal promise may be difficult to verify later.

The business should also keep track of deadlines. Missing a required payment, document request, or legal response can affect the restructuring process.

If an unauthorized or incorrect withdrawal appears, document it immediately and address it through the appropriate provider, financial institution, or professional adviser. Avoid changing accounts or blocking authorized payments without first reviewing the agreement and understanding the possible consequences.

Careful recordkeeping gives the business a clearer view of its progress and helps ensure that each provider follows the documented terms.

How Do You Choose an MCA Debt Restructuring Company?

The company you choose can affect your payments, cash flow, and ability to keep the business operating. Before enrolling in any program, confirm that the provider understands your complete financial situation and clearly explains how its services work.

A reputable MCA debt restructuring company should review your obligations before recommending a payment plan. It should also provide enough information for you to compare the proposed program with other available options.

Ask How Agreements and Cash Flow Will Be Reviewed

A restructuring company should not recommend a payment amount based on a short phone call or estimated revenue. It needs to review the business’s agreements, payment history, bank activity, and essential expenses.

Ask whether the review will include:

  • Every active MCA agreement
  • Original funding and repayment amounts
  • Current balances and withdrawal schedules
  • Factor rates and additional fees
  • Business bank statements
  • Payroll, taxes, rent, and vendor expenses
  • UCC filings and personal guarantees
  • Existing defaults or collection activity
  • Seasonal revenue changes
  • Available working capital

The company should explain how it calculates an affordable payment. That calculation should protect essential operating expenses and not commit all available cash to the program.

If the business has multiple MCAs, ask how each obligation will be addressed. Confirm whether the company will negotiate with every provider and whether all payments are included in the proposed plan.

You should also know who will communicate with MCA providers, how often you will receive updates, and what documents you must provide.

Demand Clear Fees, Written Terms, and Realistic Expectations

Request a complete written explanation of the program before making a payment or signing an agreement.

The agreement should identify:

  • The company’s service fees
  • When and how fees will be collected
  • The proposed payment amount
  • The estimated program timeline
  • Which MCA obligations are included
  • Services the company will provide
  • Actions the business must complete
  • Cancellation and refund policies
  • Possible risks and limitations
  • What happens if negotiations are unsuccessful

Ask whether the quoted payment includes both the company’s fees and the money intended for MCA providers. A low program payment can be misleading if important costs are collected separately.

The company should also explain that results can vary. MCA providers do not have to accept every proposal, and no company can know the outcome before reviewing the agreements and completing negotiations.

Realistic expectations help the business prepare for the process. You should understand the possible payment range, expected timeline, and risks before enrolling.

Watch for Guarantees, Hidden Costs, and High-Pressure Promises

Be cautious when a company promises guaranteed payment reductions, immediate settlements, complete legal protection, or the automatic removal of UCC filings and personal guarantees.

Warning signs may include:

  • Guaranteed results before reviewing any documents
  • Pressure to enroll immediately
  • Unclear or changing fees
  • Requests for large upfront payments
  • Refusal to provide written terms
  • Promises that sound too good to be true
  • Instructions to ignore providers or legal notices
  • Claims that every MCA will accept the same arrangement
  • No clear explanation of risks
  • Difficulty reaching a consistent contact person

Do not rely on verbal promises. Ask the company to include every important representation in the written service agreement.

Research the company’s history, contact information, online presence, and customer feedback. However, reviews alone should not determine your decision. Focus on the company’s process, transparency, documentation, and understanding of business cash flow.

The right restructuring company should help you understand the numbers and evaluate your options. It should not pressure you into a program that replaces one unaffordable payment with another.

Take Control of MCA Debt Before Cash-Flow Pressure Gets Worse

MCA debt restructuring business recovery plan showing five action steps, manageable payments, protected operations, and rebuilding cash reserves

MCA withdrawals can quickly reduce the cash available for payroll, vendors, taxes, inventory, and other essential expenses. The longer the pressure continues, the more difficult it may become to stabilize the business without missing payments or taking on additional funding.

Acting early gives you more time to review your agreements, calculate the total payment burden, and explore possible restructuring options. It can also help you avoid repeated overdrafts, returned withdrawals, renewal offers, and escalating collection activity.

Before making a decision, make sure you understand:

  • How much your business owes
  • How much MCA providers withdraw each week
  • What your essential operating expenses cost
  • Which UCC filings and personal guarantees remain active
  • What payment your business can realistically afford
  • How proposed restructuring fees and terms affect the total cost

A successful restructuring plan should do more than lower the immediate withdrawal. It should create a clear path forward while protecting the cash your business needs to continue operating.

Schedule a Free Consultation With MCA Shield

If MCA payments are putting pressure on your business, MCA Shield can review your agreements, withdrawals, cash flow, and operating expenses.

The goal is to help you understand your current obligations and determine whether MCA debt restructuring provides a more manageable payment strategy.

During your consultation, you can discuss:

  • Your current daily or weekly withdrawals
  • The number of active MCA agreements
  • Remaining balances and payment schedules
  • Cash-flow challenges
  • UCC filings and personal guarantees
  • Collection or default concerns
  • A payment range your business may be able to sustain

Do not wait until MCA withdrawals prevent you from covering essential business expenses. Schedule a Free Consultation With MCA Shield to review your options and take the first step toward greater financial control.

Take Control of MCA Debt Before Cash-Flow Pressure Gets Worse

MCA payment pressure can escalate quickly. Daily or weekly withdrawals may begin affecting payroll, taxes, vendors, inventory, and other essential operating expenses. Over time, the business may rely on overdrafts, delayed payments, renewals, or additional advances to keep operating.

Taking action early gives you more time to review your agreements, calculate the full payment burden, and explore available restructuring options. It may also help you address the problem before returned withdrawals, collection activity, or legal concerns make the situation more difficult.

A sustainable restructuring plan should provide more than temporary payment relief. It should protect working capital, support daily operations, and create a realistic path toward resolving the business’s MCA obligations.

Schedule a Free Consultation With MCA Shield

If MCA payments are placing your business under financial pressure, MCA Shield can help you review your current situation.

During your free consultation, you can discuss:

  • Active MCA agreements
  • Daily and weekly withdrawals
  • Remaining payment obligations
  • Business revenue and essential expenses
  • UCC filings and personal guarantees
  • Default or collection concerns
  • An affordable payment range

Every business faces different financial challenges. That is why the process begins with reviewing your agreements, cash flow, and operating needs before discussing a possible strategy.

Schedule a Free Consultation With MCA Shield to understand your options and determine whether MCA debt restructuring could help your business regain control of its cash flow.

Schedule Your Free Consultation